


Read our AgLetter Insights Q&A with author David Oppedahl next week for further insights into Seventh District farmland values and agricultural credit conditions described in this issue of AgLetter.
Farmland values
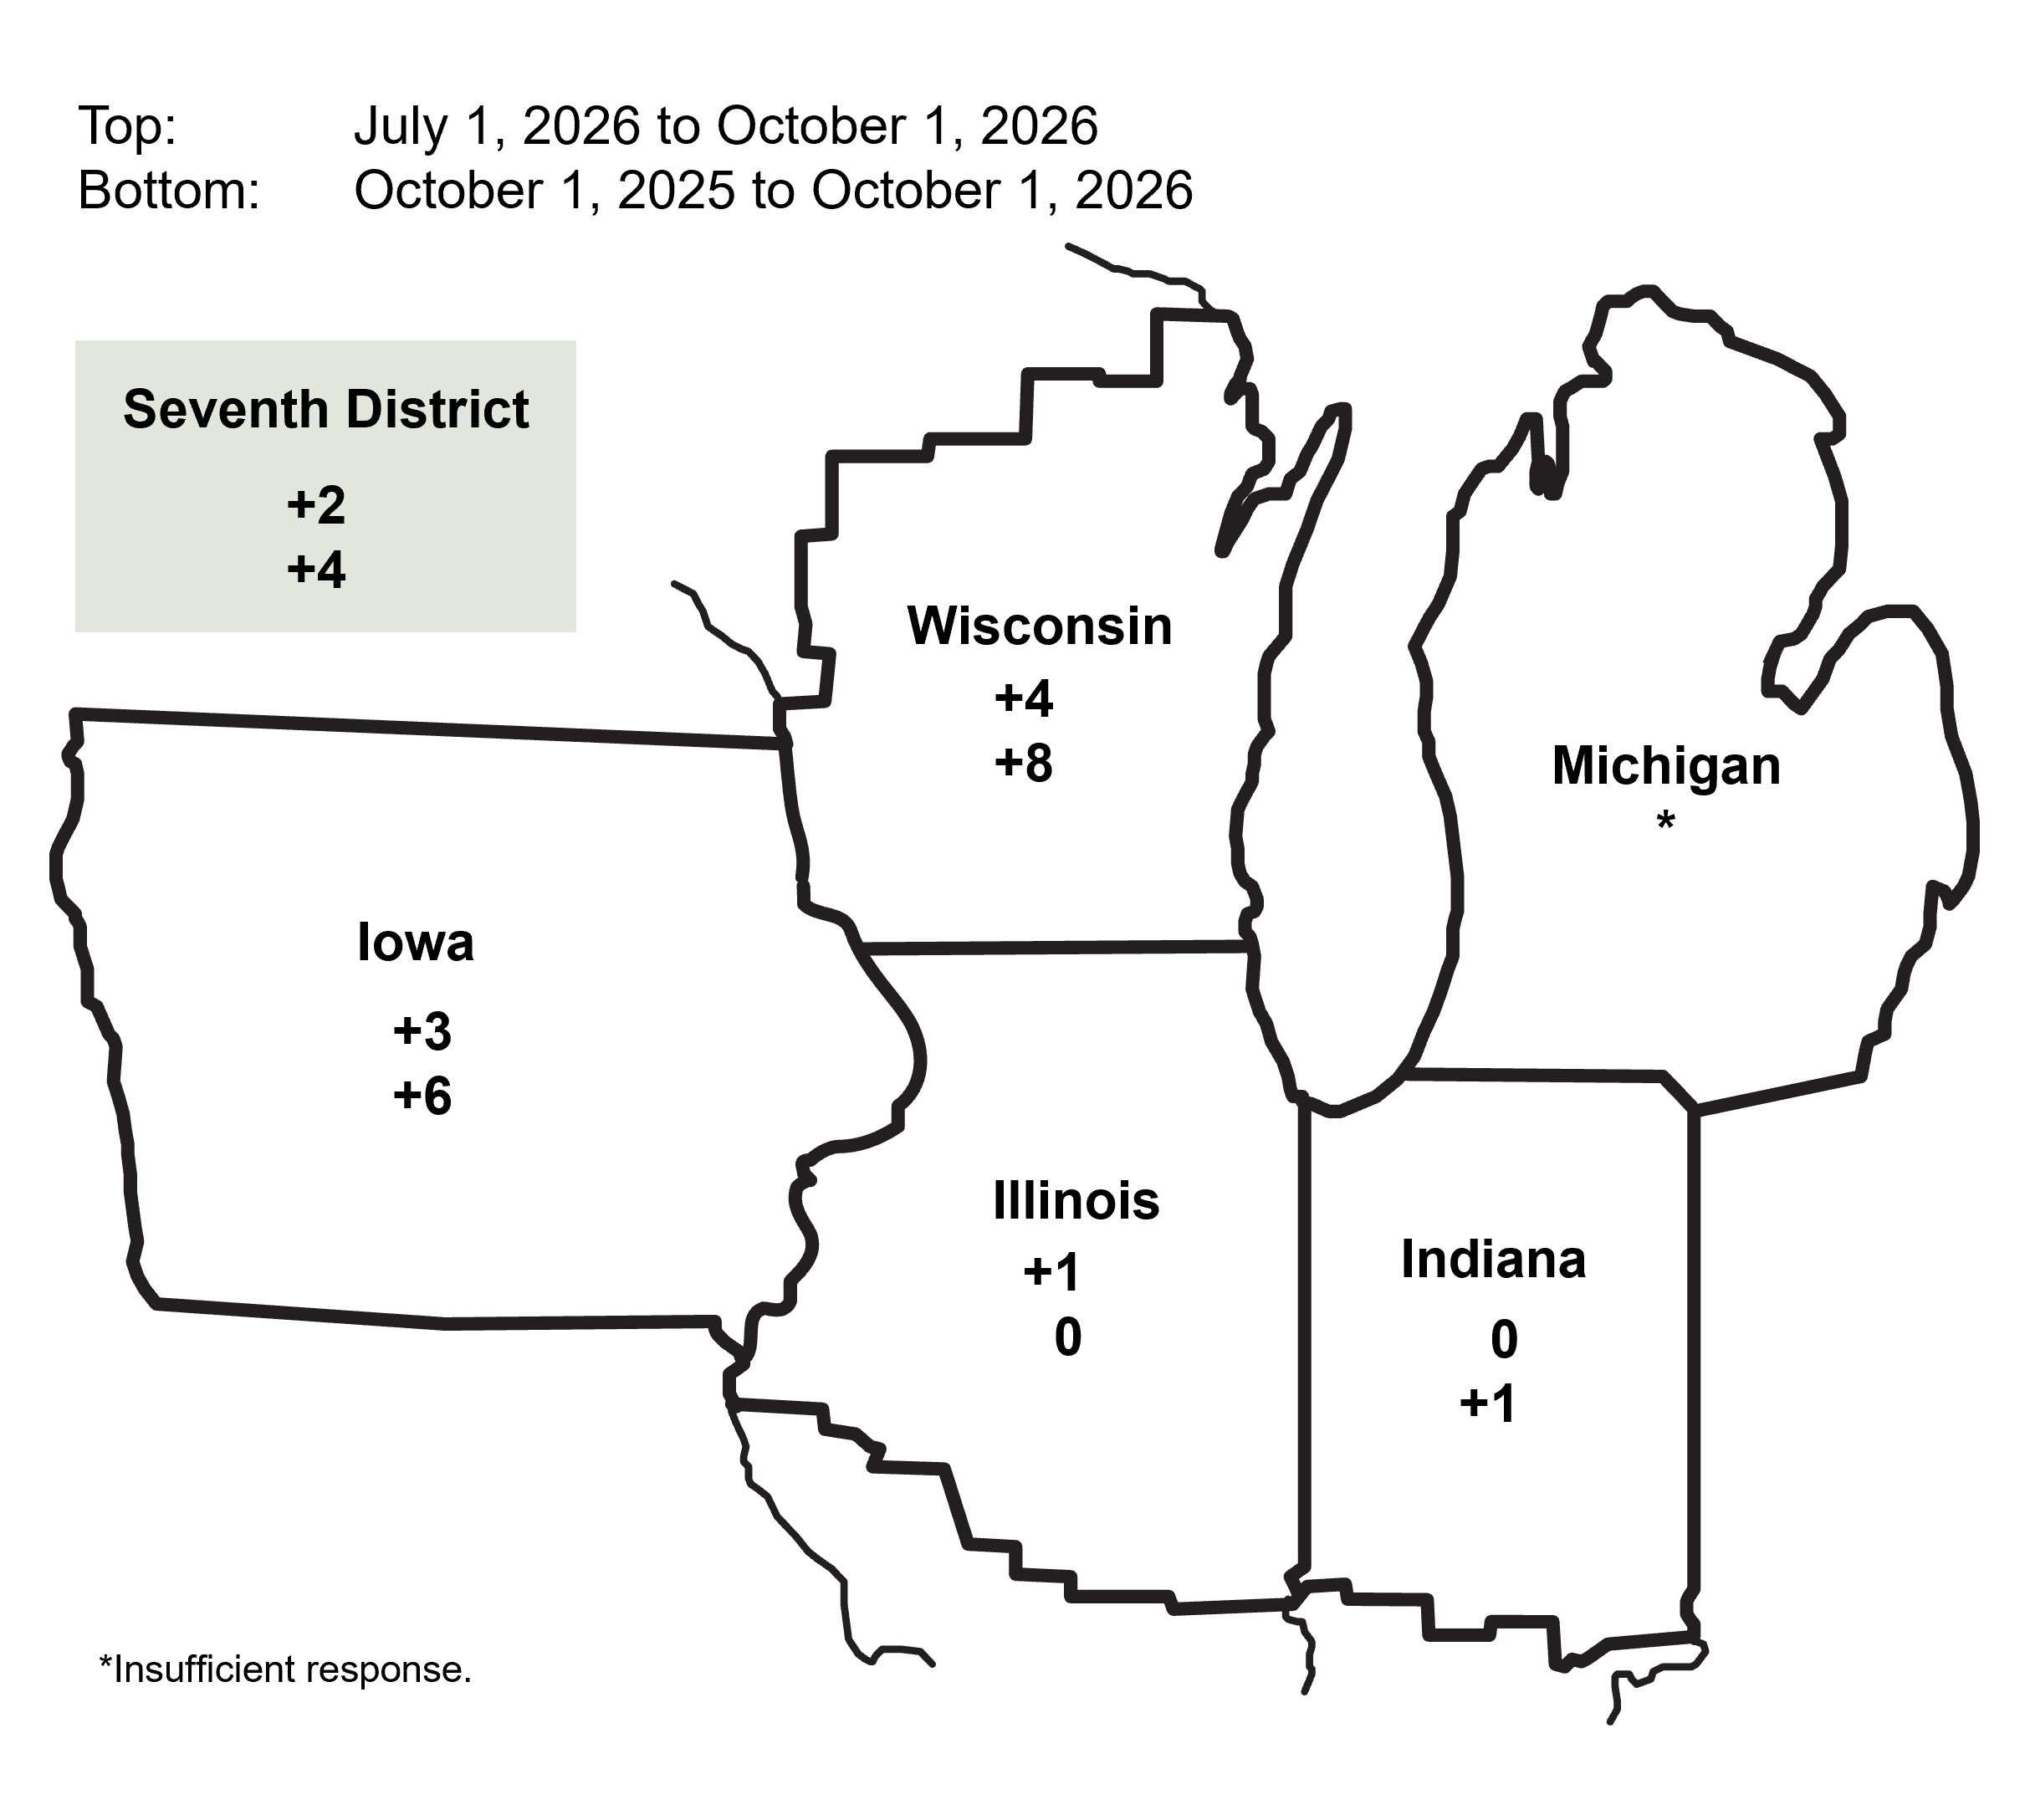
In the third quarter of 2026, the Seventh Federal Reserve District’s agricultural land values moved up 4% from a year ago, the largest year-over-year gain for a quarter in 2026 thus far. In addition, values for “good” farmland in the District overall were up 2% in the third quarter of 2026 from those in the second quarter, according to responses from 86 District agricultural lenders who completed the October 1 survey. Indiana, Iowa, and Wisconsin had year-over-year increases in farmland values, while Illinois was the only District state reporting no year-over-year change (see figure 1). There were quarterly increases in Illinois, Iowa, and Wisconsin farmland values in the third quarter of 2026; Indiana agricultural land values saw no change from the second quarter of 2026.
1. Percent change in dollar value of “good” farmland
Credit conditions
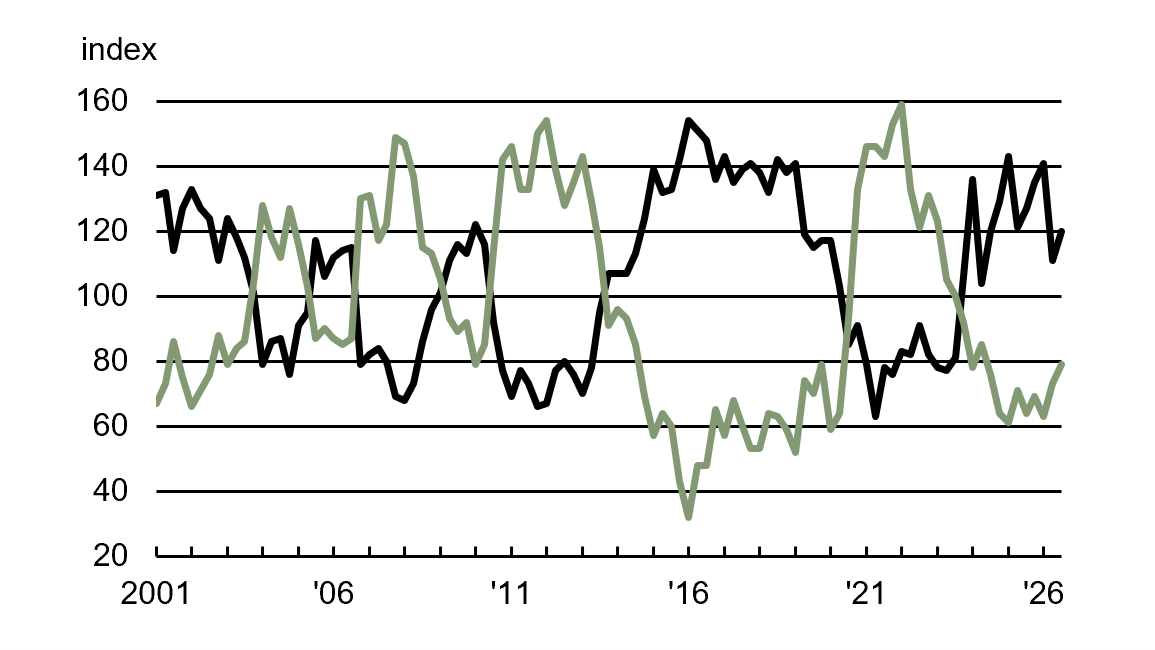
District agricultural credit conditions softened once again in the third quarter of 2026 (see figures 2 and 3). In the July through September period of 2026, repayment rates for non-real-estate farm loans were lower than a year earlier; this was the 12th quarter in a row of lower rates. In addition, renewals and extensions of non-real-estate agricultural loans were higher than a year earlier for the 13th consecutive quarter. The District still saw stronger demand for non-real-estate farm loans in the third quarter of 2026 relative to a year ago; this marked the 12th successive quarter of stronger demand. The availability of funds for agricultural lending was lower than a year ago for the 14th quarter in a row.
The breakdown of the index numbers for the third quarter of 2026 follows:
- The index of demand for non-real-estate farm loans was 120; 37% of survey respondents observed higher loan demand compared with a year ago, while 17% observed lower demand.
- The index of funds availability stood at 91; 11% of survey respondents noted that their financial institutions had more funds available to lend than a year ago, while 20% noted they had less.
- The index of repayment rates for non-real-estate agricultural loans was 79; only 3% of responding lenders noted higher rates of loan repayment than a year ago, while 24% noted lower rates.
- The index of renewals and extensions of non-real-estate farm loans was 121; 24% of survey respondents reported more of them than a year earlier, while just 3% reported fewer.
Collateral requirements for farm loans in the third quarter of 2026 rose from the same quarter of last year; 23% of the survey respondents reported that their financial institutions required more collateral, while none reported requiring less.
The District’s average loan-to-deposit ratio rose to 81.4% in the third quarter of 2026. The gap between the average loan-to-deposit ratio and the average level desired by the responding bankers narrowed from a year ago to a little above 2 percentage points, with 42% of the survey respondents answering that their respective banks were below their targeted levels.
Agricultural interest rates rose moderately during the third quarter of 2026, though operating loans and feeder cattle loans were still lower than a year ago. As of October 1, 2026, the District’s average nominal interest rates on new operating loans (7.41%) and feeder cattle loans (7.47%) were at their highest levels since the third quarter of 2025. The District’s average nominal interest rate on farm real estate loans (7.27%) climbed to its highest level since the second quarter of 2024.
2. Loan demand and repayment rates for Seventh District non-real-estate farm loans
Source: Authors’ calculations based on data from Federal Reserve Bank of Chicago surveys of farmland values.
3. Credit conditions at Seventh District agricultural lending institutions
| Latest period | Prior period | Year ago | |
|---|---|---|---|
| 2026:Q3 | 2026:Q2 | 2025:Q3 | |
| Indexesa | |||
| Loan demand | 120 | 111 | 127 |
| Funds availability | 91 | 90 | 90 |
| Loan repayment rates | 79 | 73 | 64 |
| Loan renewals and extensions | 121 | 124 | 134 |
| Average loan-to-deposit ratiob | 81.4 | 80.7 | 76.9 |
| Interest rates on farm loansc | |||
| Operating loans | 7.41 | 7.12 | 7.47 |
| Feeder cattle loans | 7.47 | 7.14 | 7.57 |
| Real estate loans | 7.27 | 6.79 | 6.82 |
Looking forward
For the final quarter of 2026, 13% of survey respondents expected District agricultural land values to rise and 14% expected them to decline (73% expected them to be stable). In line with these survey results, softer demand by agricultural producers for farmland will likely extend into 2027: 29% of survey respondents expected farmers to have weaker demand to acquire farmland this fall and winter compared with a year earlier, while 19% expected stronger demand. In contrast, 27% of survey respondents anticipated nonfarm investors to have stronger demand to purchase farmland over the same period, while 18% anticipated weaker demand from this market segment. Furthermore, responding lenders projected an increase in the volume of agricultural land transfers during this fall and winter relative to a year ago.
Net cash earnings (which include government payments) for crop farmers were expected to be lower over the next three to six months (i.e., during the fall and winter) than their levels of a year ago; 38% of survey respondents forecasted them to be higher, while 46% forecasted them to be lower. Similarly, 17% of responding lenders forecasted net cash earnings for cattle and hog farmers to increase over the next three to six months relative to a year ago, while 43% forecasted them to decrease. Only 3% of survey respondents expected net cash earnings for dairy farmers to increase over the next three to six months relative to a year earlier, while 34% expected them to decrease. An Illinois respondent stated, “The reduction of cattle prices will likely expose some marginal borrowers.”
Twenty-one percent of survey respondents anticipated a lower volume of farm loan repayments over the next three to six months relative to a year earlier (13% predicted a higher volume). Unsurprisingly, given lower crop and livestock income expectations, forced sales or liquidations of farm assets owned by financially distressed farmers were anticipated to rise in the next three to six months relative to a year ago; 31% of the responding lenders projected them to increase, while 8% projected them to decrease. Non-real-estate farm loan volumes were forecasted to be larger in the last three months of 2026 compared with the same three months of 2025, notably for operating loans and loans guaranteed by the Farm Service Agency. Farm real estate loan volumes were also forecasted to be larger in the final three months of 2026 compared with the same three months of a year earlier.
Note: The published AgLetter results are based on survey responses from commercial banks and Farm Credit System institutions located in the Seventh Federal Reserve District. All survey results prior to the first quarter of 2026 reflect survey responses from commercial banks only.


